What happened
Today’s supplied reports describe pressure points across construction, housing finance and property businesses—not one uniform national housing trend. The material consists of excerpts rather than full reports, so some explanations and context may be missing.
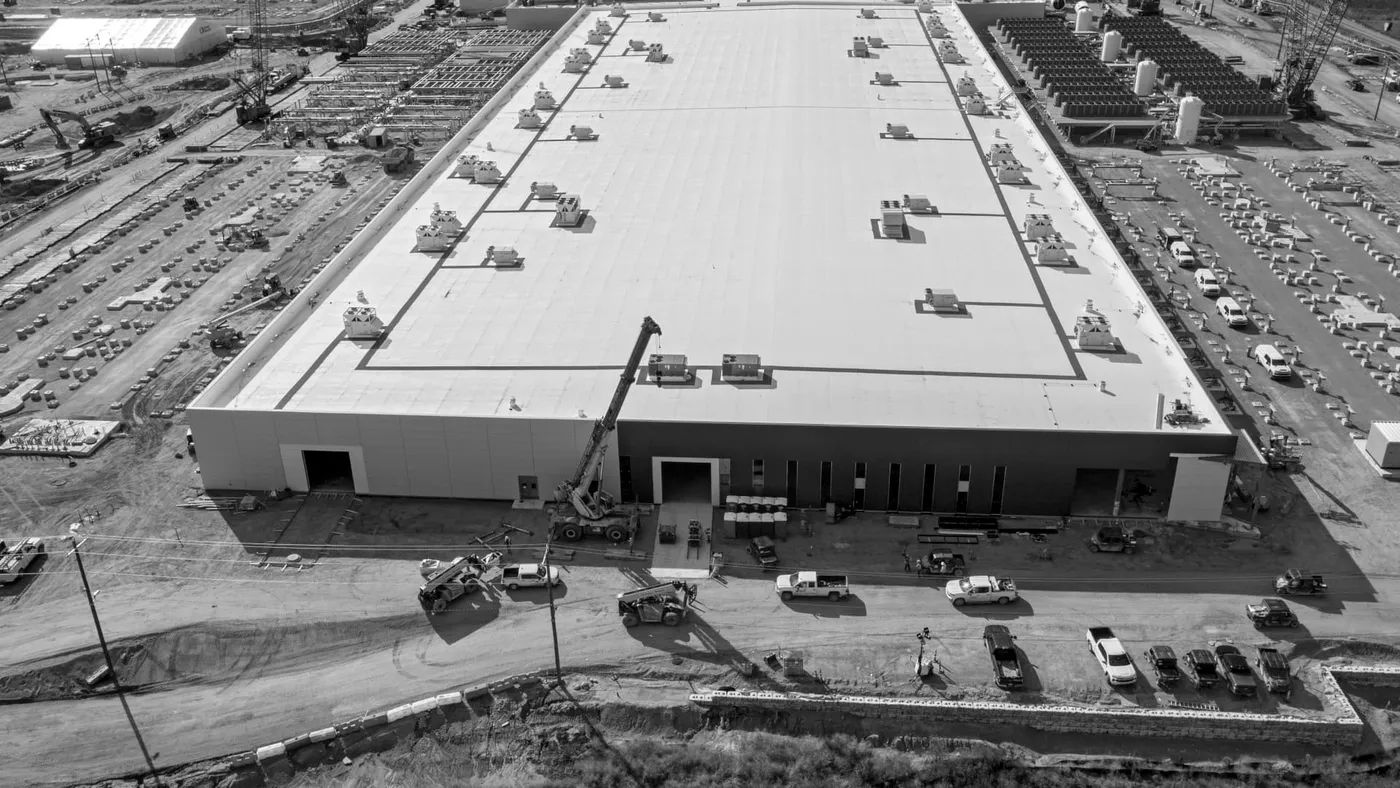
Image source: Data center construction costs soar 13% in 2026
Data-center construction costs climbed. A Turner & Townsend report covering more than 500 live or recently completed projects in 62 markets put U.S. data-center construction cost growth at 13% year over year in 2026—more than twice the global rate and about three times the U.S. ten-year average. The report and an industry executive attributed the increase to rapid AI-related demand, shortages of powered land and construction labor, supply-chain strain, and accelerated schedules that lead contractors to price in additional risk and labor allowances. Power was a major delivery obstacle for 56% of survey respondents. Costs also varied by location: the report gave $15.01 per watt in Silicon Valley and $10.51 in Dallas for a typical 60-megawatt design. Turner & Townsend’s North America data-center lead forecast more moderate cost increases of 6% to 10% over the next year; that is a forecast, not a reported outcome. [1]
FHA mortgage-insurance rules drew renewed industry calls for change. HUD’s report to Congress put the FHA insurance fund’s capital ratio at 10.29% on September 30, down from 11.47% a year earlier, but above the 2% statutory minimum. The Mortgage Bankers Association and other groups argued that the fund’s reported strength creates room for targeted affordability changes. Proposals include cutting the standard annual premium from 0.55% to 0.35% for new borrowers, or automatically ending premiums when a loan balance reaches 78% of the home’s original value. Neither is described as adopted policy. Under current rules, borrowers who put less than 10% down generally pay FHA mortgage insurance for the life of the loan; those putting down at least 10% pay for 11 years. HUD’s report says the 2023 premium cut reduced fund revenue and contributed to the lower capital ratio, but the supplied excerpt does not give a complete explanation of the year-over-year decline. [2]
Home-equity borrowing remained an important outlet for owners holding low-rate first mortgages. Benutech’s county-level mortgage-recording analysis counted more than 6 million second mortgages, including HELOCs and closed-end second liens, from January 1, 2022, through October 10, 2026. Volume peaked at 1.54 million in 2025; 953,185 had been recorded through October 10 this year, putting 2026 on pace for about 1.23 million, according to the analysis. Separately, the New York Fed reported HELOC balances rose $23 billion to $481 billion in the third quarter, the largest quarterly increase since 2005. Sources cited the mortgage-rate lock-in effect, renovations and debt consolidation as reasons for demand. These figures describe different measures and periods, not a single forecast of all mortgage borrowing. [7]
Permitting reform advanced, but has not become law. The Senate passed the Bipartisan American Affordability and Jobs Act 62–33 on Thursday. The bill would streamline federal reviews for some housing and other projects. Supporters say shorter reviews could reduce delays and development costs; opponents cited in the report argue the changes could weaken environmental protections. The bill now needs House action, with the reporting describing a potential deadline before the 120th Congress begins on January 3. Its effects on housing supply or prices remain uncertain. [8]
Homebuilder dealmaking is shifting toward execution. A homebuilding industry analysis counted more than 200 U.S. builder transactions since 2010, with more than $30 billion in announced value based on seven of the largest deals; it excludes many private transactions with undisclosed prices. The article says recent deals continued in 2026, but weak demand, sales incentives, shrinking margins and uncertainty over land and home values have made new acquisitions harder. Its central argument is that buyers must now demonstrate they can operate and integrate what they acquired, not just grow in size. [3]
Other industry developments included a proposed class action alleging Howard Hanna charged a homebuyer a $395 transaction fee without a corresponding service. The allegations concern an October 2021 purchase; the report says the brokerage had not immediately responded to a request for comment. [4] New York’s attorney general also announced an indictment alleging that Bronx broker Marcia Campbell made false disclosures on a June 2026 license-renewal application. Her license was administratively suspended; the charges and allegations are not findings of guilt. [6] Separately, FHFA stakeholder-relations director Meredith Wimbrow is leaving after about 20 months to join Federal Hall Policy Advisors. [5]
Image source: Data center construction costs soar 13% in 2026
Why it matters
The data-center figures show how a property sector can face its own local supply constraints even amid broader housing concerns. Power access, labor capacity and construction schedules are directly linked to delivery and cost in this market; the reported per-watt difference between Silicon Valley and Dallas also cautions against treating one location’s costs as a national rate. The predicted moderation in cost growth is an industry executive’s outlook, not a guarantee.
For FHA borrowers, the debate is about balancing monthly affordability with the insurance fund’s financial cushion. A lower premium or earlier cancellation could reduce costs for some borrowers, but the report also notes that the 2023 rate cut reduced fund revenue. The proposed changes therefore involve a trade-off, and the available reporting does not establish what policymakers will do.
The home-equity figures point to continued use of second liens while owners preserve existing first mortgages. That can avoid refinancing an entire low-rate mortgage, but the cited lender commentary warns that HELOCs often have variable rates and that borrowing against equity does not by itself ensure a borrower can qualify for another mortgage. The reported growth should not be read as evidence that every homeowner is borrowing or that a HELOC is necessarily the best option.
Permitting reform could affect the timing and cost of federally supported housing projects if it passes and is implemented as described. But Senate passage alone does not change the rules, and the bill’s broader environmental and infrastructure provisions make its path and consequences contested. Likewise, the homebuilder analysis suggests weaker conditions are testing the value of past acquisitions, but it is an industry assessment rather than a comprehensive measure of every builder’s performance.
My take
The strongest common thread is execution under constraints. Data-center developers are paying for speed amid scarce power and labor; builders are being judged on whether acquisitions can be operated effectively in a weaker market; and housing-finance proposals are trying to ease costs without eroding institutional safeguards. That makes it important to distinguish a policy proposal, an industry forecast and a measured result.
For housing affordability, faster permitting and lower FHA premiums are plausible avenues for relief, but neither should be treated as an immediate or guaranteed reduction in home costs. The reports offer more concrete evidence of current borrowing behavior and construction pressures than of how much proposed policy changes would ultimately help buyers or renters. On the available evidence, the near-term story is a set of targeted responses to costs and capacity constraints—not a single nationwide turn in real-estate conditions.
Sources
- [1] Data center construction costs soar 13% in 2026
- [2] Some FHA borrowers pay mortgage insurance for a decade or more. There's an industry push to change the rules
- [3] Homebuilders’ $30B buying spree has cooled; now it’s all execution
- [4] Howard Hanna sued over $395 real estate transaction fee
- [5] Stakeholder relations director Meredith Wimbrow departs FHFA
- [6] Bronx real estate broker indicted for allegedly hiding felony convictions on license renewal
- [7] Lock-in effect likely to keep HELOCs, second lien activity up through 2027
- [8] Housing groups cheer Senate passage of milestone permitting bill